Quick Answer: Yes — a non-resident can open a Swiss bank account in 2026 if a bank accepts their residence, citizenship, intended use, and documented source of wealth and funds. There is no universal minimum: account products and private-banking relationships have different requirements. Some eligible clients can complete identification remotely; a bank may still ask for an in-person meeting or further evidence. Allow several weeks and confirm the process directly with the bank before applying. This is the informational guide; if you want help choosing a suitable institution and preparing an application, see our Swiss account-opening service.
| Key Fact | Current Status — September 2026 |
|---|---|
| Non-residents eligible? | Yes — with strict KYC/AML, documented source of wealth, and minimum deposits |
| Typical timeline | 3–12 weeks (3–6 online banks; 8–12 complex/PEP cases) |
| Remote opening | Remote options depend on bank, residence, client type and verification route; confirm before applying |
| Min. deposit range | No universal minimum; distinguish a first-transfer requirement from private-banking relationship size |
| Deposit protection | CHF 100,000 per client per bank (esisuisse — automatic) |
| Tax confidentiality | CRS/AEOI reporting applies where relevant; confirm current crypto-reporting rules |
| Regulator | FINMA — Swiss Financial Market Supervisory Authority |
| Russian/Belarusian nationals | Sanctions, residence and bank policy require individual review |
| US citizens | FATCA limits options; ask each bank whether it accepts US persons |
| AML risk profile | Use our free AML Risk Score Calculator before applying |
The Truth About Opening a Swiss Bank Account as a Non-Resident in 2026
For the past 15 years, my working day has revolved around one specific challenge: helping high-net-worth individuals and corporate clients find and secure the right premium Swiss banking solution for their situation. Three of those years were spent inside a FINMA-registered Independent Asset Manager in Switzerland, where cross-border client onboarding, AML compliance reviews, and bank relationship management were daily responsibilities — not abstract concepts. That institutional experience eventually led me to build something of my own. Today, I run an independent consulting firm that works directly with foreign individuals and companies across dozens of countries — matching client profiles to the right banks, preparing documentation packages, and guiding applications through compliance review from start to finish.
From both positions — institutional insider and independent advisor — I have watched hundreds of applications move through the Swiss compliance process. Some cleared in weeks. Others collapsed at the first review. Rarely did a failure come down to the client’s legitimacy. Almost every time, it came down to preparation.
What This Guide Covers and Who It Is For
This guide covers every material aspect of opening a Swiss bank account as a non-resident in 2026. Inside, you will find a 17-bank comparison with published conditions and indicative relationship sizes, a step-by-step process with realistic timelines, a full documentation checklist, a complete fee comparison, and three detailed case studies drawn directly from my own client work.
Non-residents who benefit most from this guide fall into several clear categories. Some are entrepreneurs who have built and sold businesses and now want to diversify their assets into a politically stable currency. Others are senior professionals relocating internationally who need a reliable multi-currency banking base. Many are families managing cross-border wealth across multiple jurisdictions. A smaller group are digital asset holders seeking regulated Swiss custody solutions that no other country currently matches.
Regardless of which category fits your situation, one principle applies consistently across all of them. Swiss banks in 2026 do not primarily assess whether you are wealthy. They assess whether your wealth is explainable. That shift in emphasis — from the size of your assets to the clarity of their origin — defines the modern Swiss compliance environment. Consequently, the quality of your source-of-wealth documentation matters far more than most applicants expect.
⚠️ Bank-specific eligibility and prices were checked on 23 September 2026 where a primary source is cited. Other comparison figures are indicative, not a bank offer. Requirements for Indian nationals and other cross-border clients can change. Confirm current terms with your chosen institution before applying.
1. Why Swiss Banking Still Leads in 2026
Political Neutrality and Economic Stability
Switzerland’s constitutionally enshrined neutrality remains its most powerful financial asset. Unlike other jurisdictions, Swiss-held assets are insulated from abrupt government freezes and capital controls. This architectural stability has endured through two world wars, the 2008 financial crisis, and ongoing geopolitical turbulence.
In the first five months of 2026, banks in Switzerland managed CHF 10.1195 trillion in client assets, up from CHF 9.7291 trillion at end-2025, according to the Swiss Bankers Association’s Banking Barometer 2026. Switzerland maintains AAA sovereign credit ratings from Moody’s, S&P, and Fitch — all three major agencies. GDP growth reached 1.4% in 2025 and is projected at 1.6% for 2026, providing a stable macroeconomic backdrop for banking relationships.
Following the 2023 UBS acquisition of Credit Suisse, UBS became Switzerland’s sole globally systemically important bank (G-SIB). The Federal Council’s June 2025 stability package — including a public liquidity backstop — further reinforced the system’s resilience. As a result, institutional confidence in Swiss banking remains at historic highs. The next chapter is the post-Credit Suisse overhaul of UBS’s new capital requirements and what they mean for depositors.
Political Neutrality & Economic Stability
Switzerland’s constitutionally enshrined neutrality remains its most powerful financial asset. Unlike other jurisdictions, Swiss-held assets are completely insulated from abrupt government freezes and capital controls.
Architectural Stability Tested By Time
Regulatory Excellence Under FINMA
The Swiss Financial Market Supervisory Authority (FINMA) supervises banks’ compliance with Swiss anti-money-laundering requirements. Institutions screen applicants against relevant sanctions and risk information, but no single commercial database is mandatory for every Swiss bank. A bank’s review may cover political exposure, beneficial ownership, source of wealth and adverse media.
A screening match prompts the bank to check whether the record truly concerns the applicant and whether further due diligence is needed. A politically exposed person or another elevated-risk profile may require more evidence, senior approval and closer monitoring under the bank’s risk procedures. A database match alone is not proof of wrongdoing.
What Swiss Banking Confidentiality Means in 2026
Swiss banking confidentiality operates under two distinct regimes. Against private third parties, bank-client confidentiality remains robustly protected under the Swiss Banking Law. It is comparable to attorney-client privilege. Unauthorised disclosure carries criminal penalties: up to six months imprisonment for unintentional breaches and up to three years for deliberate violations.
However, tax confidentiality ended in 2017. Switzerland participates in the OECD Common Reporting Standard (CRS) with over 110 countries. Banks automatically transmit non-resident account data — name, address, tax identification number, account balance, and annual investment income — to home-country tax authorities each year.
Switzerland’s State Secretariat for International Finance says crypto-asset AEOI under CARF cannot start before 1 January 2027; partner-state implementation remains subject to decisions. Existing financial-account AEOI/CRS already limits tax secrecy for reportable non-resident accounts. Bank-client confidentiality still protects against unauthorised private disclosure.
“The decisive factor today is not anonymity but capital quality. Your primary task is proving the legal origin of your funds.” — FINMA-Certified Banking Specialist
World-Class Wealth Management Infrastructure
Swiss banks remain a major centre for cross-border private wealth management. The Swiss Bankers Association reports CHF 2.9457 trillion in cross-border private-client holdings at end-2025. This is a narrower category than the CHF 10.1195 trillion in total client assets managed by banks in Switzerland in the first five months of 2026. This infrastructure reflects centuries of expertise in cross-border tax, legal, and compliance frameworks.
Deposit protection further reinforces security. The statutory guarantee scheme, esisuisse, protects deposits up to CHF 100,000 per client per bank. This applies automatically in any bank insolvency scenario and covers both Swiss franc and foreign currency deposits.
2. Who Can Open a Swiss Bank Account in 2026?
Eligibility to Open a Swiss Bank Account as a Non-Resident
Swiss banks welcome a broad range of international clients. However, eligibility depends heavily on your financial profile, country of residence, and source of wealth. The following categories represent the primary client groups that Swiss institutions actively serve in 2026.
High-Net-Worth and Ultra-High-Net-Worth (HNWI / UHNW) Individuals
This is the most direct path to Swiss private banking. Institutions such as Pictet, Lombard Odier, UBP and UBS Private Wealth assess the proposed relationship and service level individually. Lombard Odier says clients typically entrust more than CHF 1 million in liquid assets, with variation by service and residence; do not treat a single figure as a universal minimum for the group. Clients may access bespoke investment strategies and family-office services where eligible. Source-of-wealth documentation must be comprehensive and independently supportable.
Affluent Professionals and Entrepreneurs
Senior executives, successful founders and international consultants may find an appropriate private-banking relationship depending on their investable assets and needs. Julius Baer and Axion Swiss Bank are among the institutions to assess, but eligibility and relationship size are case-specific. Services can include tailored lending, fiduciary arrangements and structured investment products. Clear professional and source-of-funds records support an application.
Mass Affluent and Online Trading Clients
Swissquote and Dukascopy serve eligible clients who need investment, trading and multi-currency capabilities without a private-banking relationship. Digital onboarding is available for some applicants, subject to residence, identity checks and product choice. Swissquote publishes a first-transfer requirement of EUR 500 for listed euro-area residents or CHF 500 for other non-residents; the sending account and country must also qualify. Check eligibility before assuming either bank will accept an application from your jurisdiction.
Cryptocurrency and Digital Asset Holders
Sygnum Bank and Amina Bank — both FINMA-licensed since 2019 — specialise in regulated digital asset banking. Their products and client criteria differ. Sygnum says it does not onboard retail clients; a private qualified investor generally needs at least CHF 500,000 in assets, and Sygnum requests at least CHF 50,000 in initial deposit or trading volume for that category. Crypto-origin wealth may require a traceable transaction history and supporting tax and exchange records; ask the chosen bank what evidence it needs.
EU and EEA Cross-Border Workers
G-permit holders working in Switzerland, and residents in bordering German, French, Austrian, and Italian regions, can access retail banking at PostFinance and Migros Bank. Requirements are more accessible. However, these accounts are primarily designed for everyday banking rather than complex international investment services.
Swiss Citizens Living Abroad (Auslandschweizer)
Swiss nationals abroad may have account options that are unavailable to other non-residents. Zürcher Kantonalbank, for example, publishes an offer for Swiss citizens abroad with no minimum deposit. Citizenship does not grant universal access to every Swiss bank or product: residence, intended use and the bank’s policy still matter.
Eligibility & Requirements Matrix
A comparison of client profiles, likely service tiers and institutions. The animated bars are illustrative; they do not show published account minimums or approval odds.
Key Restrictions: Who Faces Additional Hurdles
While many international clients are eligible, certain profiles face significant regulatory barriers. Screen sanctions, residency and bank policy before applying; an application outcome is always institution-specific.
| Profile | Eligible? | Key Issue | Path Forward |
|---|---|---|---|
| Russian / Belarusian nationals | Case-specific | Current sanctions and bank risk policy may restrict deposits or services | Check SECO rules, residence, beneficial ownership and source of funds with the bank |
| US citizens / Green Card holders | Very limited | FATCA reporting and bank licensing policies narrow the choice | Ask whether the bank accepts US persons and which products it can offer |
| FATF high-risk jurisdiction residents | Possible — with EDD | Enhanced due diligence; annual surcharges CHF 500–2,000 | Thorough SoW documentation; budget 8–12 weeks |
| PEPs and EEPs | Yes — enhanced DD | Senior management approval; quarterly monitoring; up to CHF 2,000/yr fees | Multi-layered SoW; transparent risk communication; professional introduction |
| EU/EEA cross-border workers | Yes — easier path | Retail banks preferred; limited to everyday banking | G-permit / residency proof; PostFinance or Migros Bank |
| Swiss citizens abroad | Yes — easiest path | Proof of Swiss citizenship only | Full banking access; standard onboarding |
⚠️ Important: If sanctions, US-person status, political exposure or a high-risk jurisdiction affect your profile, confirm eligibility with the bank and prepare a complete, accurate disclosure before applying. A rejection by one institution does not establish a universal ban.
3. Swiss Banks to Assess as a Non-Resident: 17-Bank Comparison (2026)
Selecting a bank whose product, geographic scope and client criteria fit your circumstances can save an avoidable application. The comparison below covers 17 institutions, including private banks and banks with broader services for entrepreneurs. Inclusion is not confirmation that a bank accepts every non-resident; eligibility and relationship size must be checked for your profile.
| Bank | Deposit / relationship size for non-residents | Remote Opening | Best For — 2026 |
|---|---|---|---|
| UBS Private Wealth | Case-specific; ask UBS | Hybrid (video + in-person) | Ultra-HNW, family offices, global reach |
| Pictet & Cie | Case-specific; ask Pictet | Relationship manager | Heritage private banking, alternative investments |
| Lombard Odier | Typically >CHF 1M in liquid assets; varies | In-person preferred | ESG / sustainable investing, next-gen wealth |
| Union Bancaire Privée (UBP) | Case-specific; ask UBP | In-person preferred | Alternative assets, boutique investment service |
| Julius Baer | Case-specific; ask Julius Baer | Relationship manager | Emerging markets, art financing (tightened Q1 2026) |
| Axion Swiss Bank | Case-specific; ask Axion | In-person preferred | Accessible private banking, EU residents, ESG focus |
| Bank J. Safra Sarasin | Case-specific; ask bank | Relationship-led; confirm | International private banking and wealth management |
| Rothschild & Co Bank AG | Case-specific; ask bank | Relationship-led; confirm | Families and entrepreneurs; wealth planning and financing |
| BIL Suisse | Case-specific; ask bank | Relationship-led; confirm | Private and corporate banking, finance for entrepreneurs |
| Banca del Sempione | Case-specific; ask bank | Relationship-led; confirm | Ticino private banking, entrepreneurs and businesses |
| Swissquote Bank | First transfer: EUR/CHF 500 for eligible non-residents | Fully online | Online trading, mass affluent, CIS/global clients |
| Dukascopy Bank | Product-dependent; ask Dukascopy | Fully online | Forex, multi-currency, digital nomads |
| Sygnum Bank | Qualified investors: CHF 500K assets; CHF 50K relationship | Eligibility-dependent | Qualified investors and institutional digital assets |
| Amina Bank | Product-dependent; confirm with AMINA | Eligibility-dependent | Digital-asset banking; product fit varies |
| PostFinance | No universal CHF 1M requirement published | Case-specific | Limited products for eligible clients abroad |
| Migros Bank | Residence/product-dependent; ask Migros | Online (limited) | EU/EEA residents, SME |
| Zürcher Kantonalbank (ZKB) | Citizens abroad: no minimum on listed offer | Online (limited) | Cantonal retail, Swiss residents preferred |
📌 These are product and relationship indicators, not guaranteed acceptance thresholds. The published examples come from Swissquote, Sygnum, Lombard Odier, PostFinance and ZKB. The new private-bank profiles below link to their own service descriptions. Confirm current terms and residence eligibility for your exact account with each bank.
In-Depth Profiles: Key Banks for Non-Residents
UBS Private Wealth — Global Scale and Digital Excellence
UBS is the world's largest wealth manager, with CHF 5.2 trillion in assets under administration as of end-2025. It serves ultra-HNW and family office clients through AI-powered portfolio analytics, relationship managers in over 50 countries, and bespoke credit solutions. Following the Credit Suisse integration, UBS has significantly expanded its product range and compliance infrastructure. Preliminary applications use AI-powered document verification. A secure video interview typically follows within 48 hours. In-person meetings are preferred — but not always mandatory — for final approval.
Pictet & Cie — Heritage, Alternatives, and Family Office Focus
Pictet has operated as a partnership since 1805. It manages CHF 620 billion and maintains a strict family-office and alternatives focus unavailable at larger institutions. Services include private equity, hedge funds, and structured products with favourable access terms for existing clients. Applications typically begin through professional network introductions. Approval takes 4–6 weeks after comprehensive financial profiling and a multi-stage compliance review.
Lombard Odier — Sustainability Pioneer
Lombard Odier manages CHF 310 billion with an industry-leading ESG focus. It pioneered carbon-neutral portfolios and embeds climate considerations across all asset classes. The bank strongly appeals to next-generation investors and impact-focused families. Its digital advisory platform combines traditional relationship management with algorithmic portfolio construction. International applications are accepted, though in-person meetings are strongly preferred.
Bank J. Safra Sarasin — International Private Banking
Bank J. Safra Sarasin is a Swiss private-banking group with international wealth-management activity. Its 2025 annual report describes private-client services across several jurisdictions. For a non-resident, confirm which legal entity would hold the account, which services it can provide in the client's country, and the proposed relationship size; no universal Swiss minimum is stated here.
Rothschild & Co Bank AG — Families and Entrepreneurs
Rothschild & Co's Swiss wealth-management business serves families, entrepreneurs and executives in Switzerland and internationally. Its published offering combines investment management and wealth planning with private banking, Lombard lending and real-estate financing. Cross-border eligibility, the booking entity and any relationship size should be checked for the specific client and service.
BIL Suisse — Private Banking and Corporate Finance for Entrepreneurs
BIL Suisse combines private banking with corporate and institutional banking services. Unlike a wealth-management-only mandate, its Swiss Global Advisory team offers corporate finance advice, debt and equity advice, M&A support and structured lending for entrepreneurs and family-owned businesses. Its lending team also describes Lombard credit, international mortgages and tailored financing facilities. This wider offering may suit a foreign entrepreneur who needs to discuss personal assets, a company relationship and financing together. A corporate account or credit facility is never automatic; the Swiss entity must confirm jurisdiction, business activity, collateral and credit eligibility.
Banca del Sempione — Ticino Private Banking with Business Services
Banca del Sempione, based in Lugano, publishes discretionary and advisory mandates, execution-only investing and financing solutions. It also describes services for entrepreneurs and businesses and an international outlook. Ask the bank whether your residence and intended personal or corporate use fit its current policy; no general non-resident minimum is published in the material reviewed.
Swissquote — Best for Digital-First Non-Residents
Swissquote is an online bank that may suit eligible non-residents seeking investment and trading services. For the Swiss entity, its published first-transfer requirement is EUR 500 for residents of listed euro-area countries or CHF 500 for other non-residents; the transfer must come from an account in the applicant's name at a licensed bank in an accepted country. Identity verification and available products depend on residence. Check Swissquote's current eligibility and fees directly before applying.
Dukascopy Bank — Multi-Currency and Forex Specialist
Dukascopy is a FINMA-licensed Swiss bank with no stated minimum deposit. It is particularly strong for forex trading, multi-currency accounts, and clients with global nomadic lifestyles. The Dukascopy Connect app enables transfers, payments, currency exchange, and virtual card issuance entirely from mobile. Onboarding is fully remote and typically completes within 3–5 weeks for straightforward profiles.
Sygnum and Amina Bank — Regulated Crypto Banking
Sygnum and Amina Bank are Swiss-regulated digital-asset banks with different products and entry criteria. Sygnum states that it does not onboard retail clients and lists criteria for private qualified investors. Amina offers several account and investment services with product-specific conditions. For either, explain how digital assets were acquired, traded and converted, and ask the bank which transaction and tax records it needs for your profile.
4. Complete Documentation Requirements — 2026
Documentation quality is the single biggest determinant of approval speed and success. Banks cannot proceed with incomplete applications. Moreover, they typically restart the compliance review clock when supplementary documents arrive after initial submission. Prepare everything before you submit anything.
| Document | Specification | Who Needs It |
|---|---|---|
| Certified passport copy | Valid 6+ months beyond application; notarised or apostilled | All applicants |
| Secondary ID | National ID or driver's licence | High-risk / EDD cases |
| Proof of address | Utility bill or bank statement — dated within 3 months | All applicants |
| Source of Wealth (SoW) | Tax returns, business financials, sale agreements, clear narrative | All applicants |
| Employment verification | Payslips (last 3 months), HR letter, employment contract | Employed professionals |
| Audited financial statements | 2 years minimum; for business owners and entrepreneurs | Self-employed / founders |
| Business registration docs | Certificate of incorporation, articles of association | Corporate accounts |
| UBO disclosure | Full beneficial ownership chain to natural persons | Corporate accounts |
| Brokerage / investment statements | 12-month transaction history and current positions | Investors / HNWIs |
| Blockchain transaction history | 12+ months from recognised exchanges; wallet proof | Cryptocurrency holders |
| PEP/EEP risk questionnaire | Senior management approval; quarterly reviews required | PEPs and EEPs |
| Tax residency certificate | Current jurisdiction residency; supporting returns | Russian/Belarusian applicants |
Understanding Your Source of Wealth
The Source of Wealth (SoW) declaration is your most important document. It must clearly narrate how your assets accumulated, supported by independent documentary evidence. Banks in 2026 are increasingly requesting 5–10 year financial histories, particularly for clients from emerging markets or with complex business structures.
Common acceptable sources include: employment income (payslips, HR letters), business ownership (audited financials, shareholding records, sale agreements), investment returns (brokerage statements), inheritance (probate documents, estate certificates), and real estate proceeds (sale contracts, valuations). For cryptocurrency wealth, a bank may ask for blockchain transaction history, exchange statements and proof of initial funding.
Check Your AML Risk Profile Before Applying
Swiss banks conduct rigorous AML risk assessments on every non-resident application. Your country of residence, profession, business structure, fund origin, and transaction patterns all contribute to your risk score. A high risk score triggers enhanced due diligence, extends timelines by weeks, and can lead to rejection at many institutions. Therefore, we strongly recommend running your profile through our free AML Risk Score Calculator before submitting any application. It identifies potential red flags in advance — giving you the opportunity to address them before they become rejection reasons.
World-Check Screening: What It Means for You
Swiss banks screen applicants against sanctions and other risk information using their own providers and procedures. A screening match is reviewed; it does not automatically mean rejection. Political exposure, a sensitive industry or a higher-risk jurisdiction may lead to more questions about beneficial ownership, source of wealth and the first transfer. Disclose relevant facts accurately and ask the bank what evidence it needs.
5. Step-by-Step Account Opening Process with Real Timelines
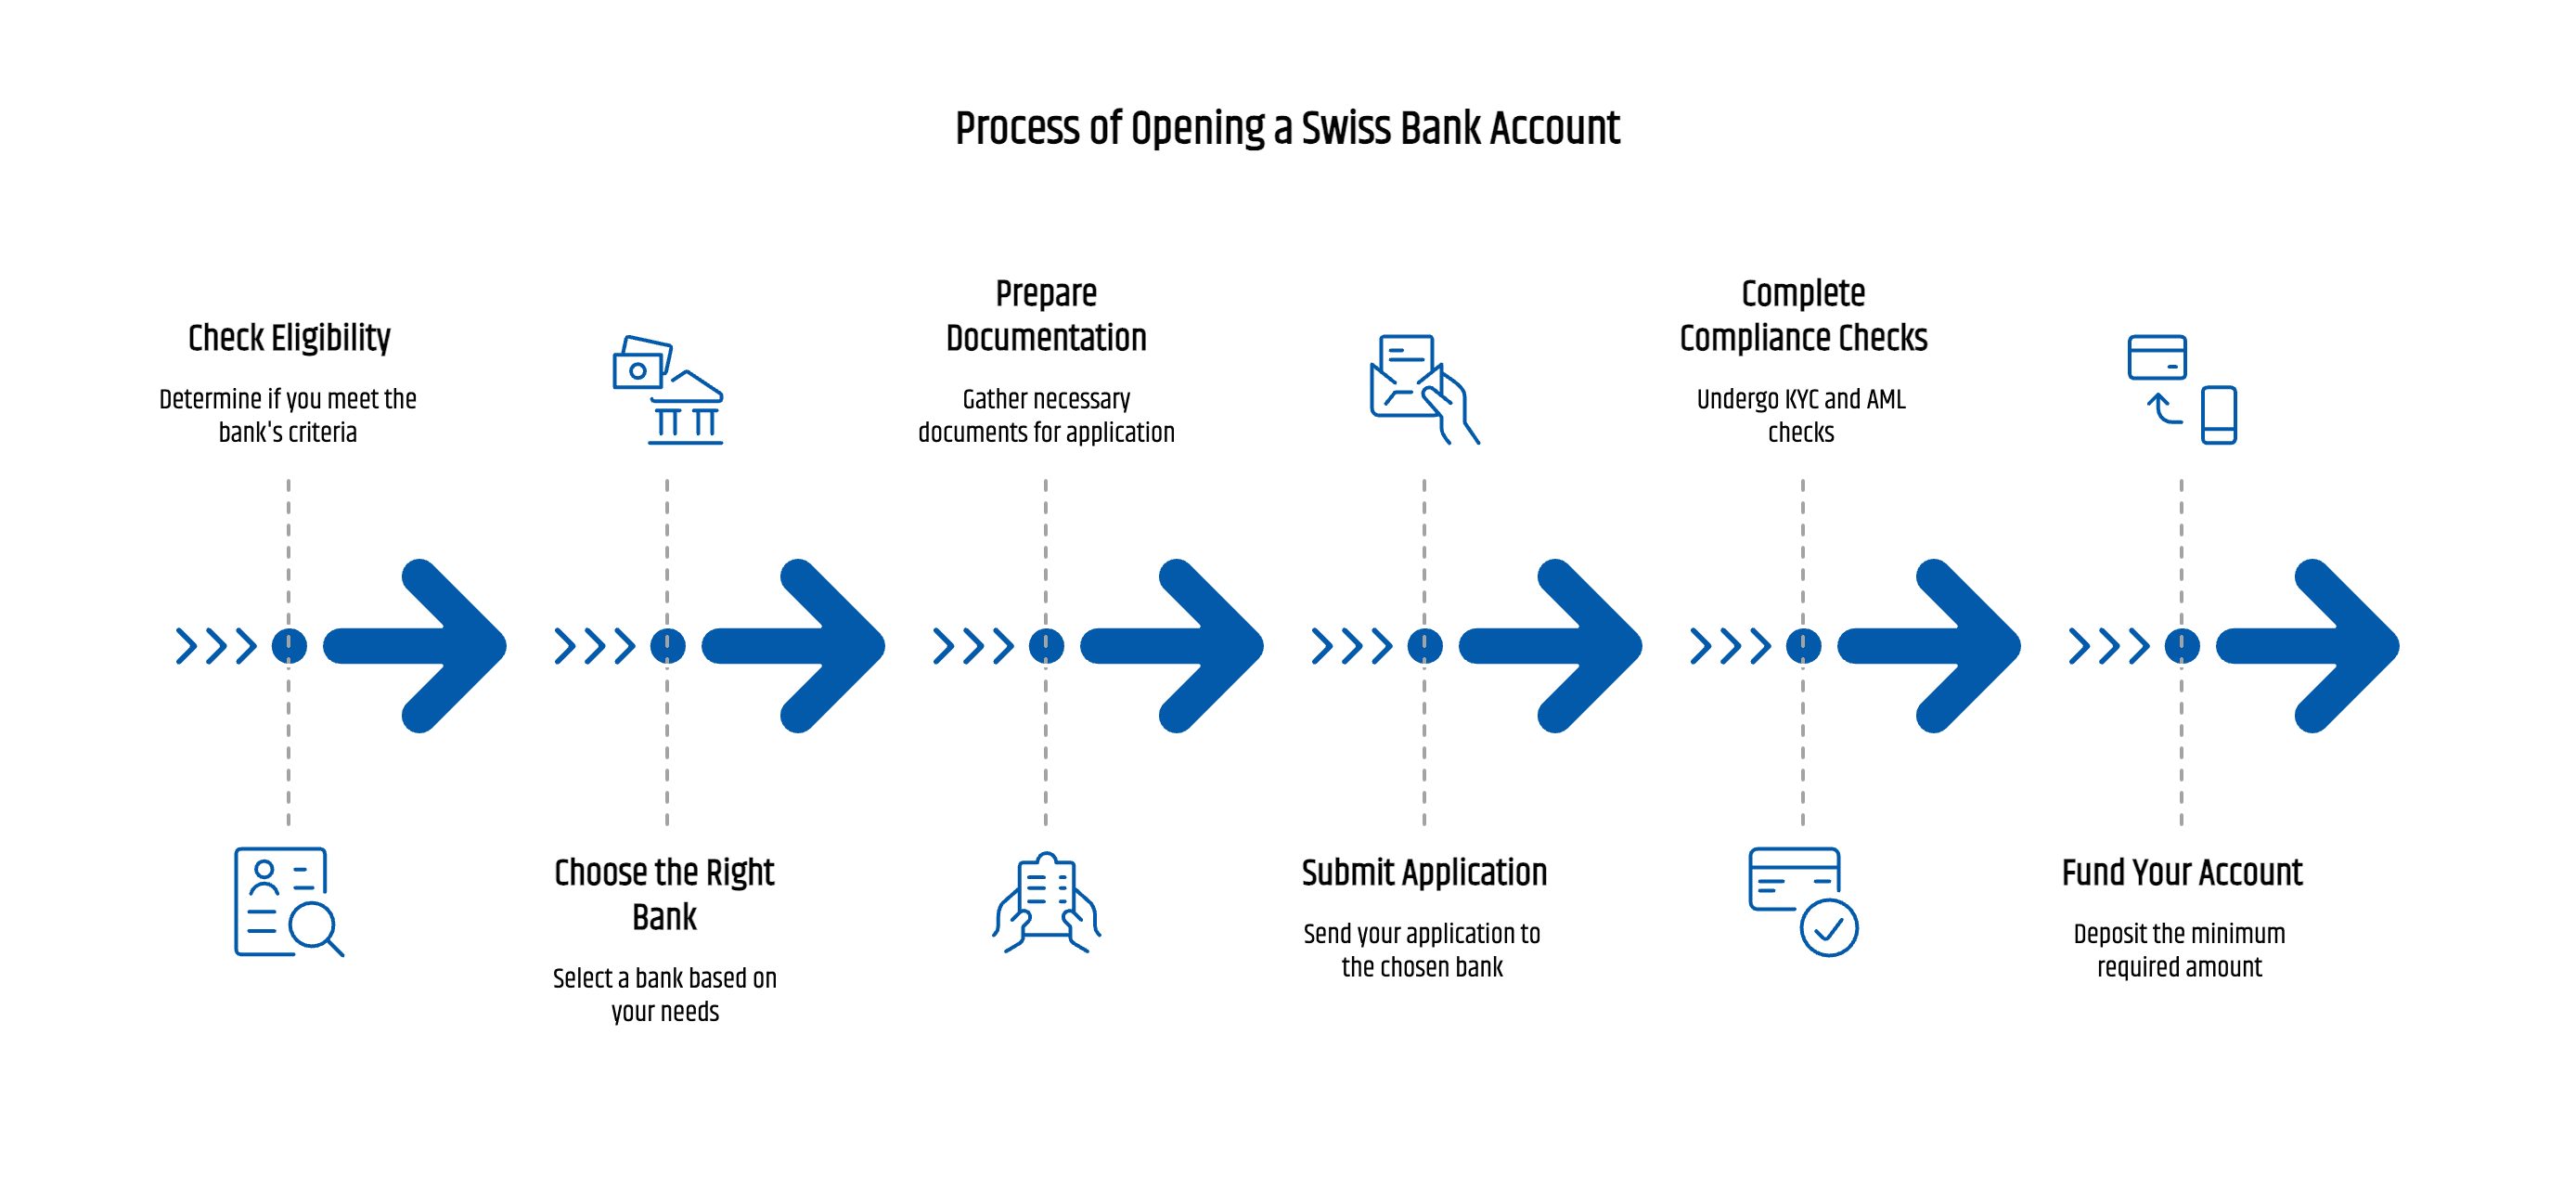
| Phase | What Happens | Duration |
|---|---|---|
| 1. Strategic Preparation | Bank research, profile matching, document assembly | 1–2 weeks |
| 2. Application Submission | Online forms, document upload, RM introduction | 1–3 business days |
| 3. KYC & Identity Validation | Video call, biometric check, World-Check screening | 2–5 business days |
| 4. Compliance & Credit Review | SoW analysis, AML check, credit committee presentation | 5–15 business days |
| 5. Approval & Account Setup | IBAN, service configuration, agreement signing | 1–3 business days |
| 6. Deposit & Full Activation | Wire transfer, card issuance, online banking access | 6–13 business days |
| TOTAL — Digital banks | e.g. Swissquote, Dukascopy | 3–6 weeks |
| TOTAL — Private banks | e.g. Pictet, Lombard Odier, UBP | 6–8 weeks |
| TOTAL — Complex cases | PEP/EEP, high-risk jurisdictions, corporate structures | 8–12 weeks |
Phase 1: Strategic Preparation — 1 to 2 Weeks
This is where most applicants underinvest — and where most delays originate. Start by matching your financial profile to bank eligibility criteria: deposit capacity, geographic restrictions, service needs, and digital versus in-person preference. Shortlist two or three institutions. Then assemble your complete document package. Obtain certified translations for any non-English, non-German, non-French, and non-Italian documents. Secure notarisations and apostille certifications where required.
A professional pre-submission audit at this stage typically saves weeks downstream. Our Swiss bank account opening service includes a full document review and bank matching consultation before you submit a single form.
Phase 2: Application Submission — 1 to 3 Business Days
Complete the bank's online onboarding forms and upload scanned documents via secure encrypted portals. For private banking clients, schedule a preliminary consultation with your assigned relationship manager. Discuss investment objectives, service expectations, and account structure. Review fee schedules and service agreements before proceeding. Having a professional introduction to the relationship manager at this stage significantly improves processing speed and approval probability.
Phase 3: KYC and Identity Validation — 2 to 5 Business Days
Banks conduct biometric facial recognition matching against passport photographs, live document authenticity verification via video call, and automated World-Check screening. PEP or EEP clients, and those from high-risk jurisdictions, trigger enhanced due diligence at this stage. Expect additional compliance interviews, senior management review, and requests for supplementary documentation.
Phase 4: Compliance and Credit Review — 5 to 15 Business Days
The bank's credit and compliance committee reviews the complete client dossier. This includes authenticating employment, business, and investment documentation; tracing cross-border fund flows for clients with complex international structures; conducting AML and counter-terrorism financing assessment; and evaluating overall credit risk. The committee can approve, request additional information, or decline. Additional information requests reset the timeline. Consequently, complete documentation on first submission is critical.
Phase 5: Approval, Setup, and Activation — 7 to 16 Business Days
Upon committee approval, you receive formal notification with account terms, fee schedules, and deposit instructions. IBAN assignment, service package configuration, and investment platform activation follow within 1–3 business days. You then wire the required minimum deposit. After AML clearance — typically 1–3 business days — full service activation including card issuance, online banking, and mobile app setup takes a further 5–10 business days.
How to Accelerate Your Swiss Bank Account Opening
- Engage a specialist for a comprehensive pre-submission document audit before applying
- Target banks with digital onboarding capabilities matched to your client profile
- Submit 100% complete documentation on first submission — partial submissions always cause delays
- Leverage professional network introductions to relationship managers, bypassing cold-application screening layers
- Prepare proactively for additional information requests — have a secondary evidence set ready from the outset
6. Swiss Bank Account Fees for non-resident clients: Full 2026 Comparison
Free accounts for non-residents are effectively non-existent in Switzerland. Every banking relationship involves multiple cost layers. Understanding them before opening an account enables accurate financial planning and effective fee negotiation.
| Bank | Monthly Fee | Non-Resident Surcharge | High-Risk Annual | Wire Transfer | Inv. Mgmt Fee |
|---|---|---|---|---|---|
| UBS Private Wealth | CHF 50–100 | CHF 50 | CHF 1,000–2,000 | CHF 20 + % | 0.5%–1.5% |
| Pictet & Cie | Negotiable | Included | Custom | Custom | 1.0%–2.0% |
| Lombard Odier | Negotiable | Included | Custom | Custom | 0.8%–1.8% |
| UBP | CHF 50–150 | Included | CHF 1,000–2,000 | CHF 25 | 0.8%–1.8% |
| Julius Baer | CHF 50–120 | Included | CHF 1,000–2,000 | CHF 20 | 0.7%–1.7% |
| Axion Swiss Bank | CHF 25–50 | CHF 25 | CHF 500–1,500 | CHF 10–30 | 0.6%–1.2% |
| Swissquote | CHF 10–25 | CHF 15 | CHF 500–1,000 | CHF 10 | 0.95% (robo) |
| Dukascopy | CHF 0–20 | None stated | N/A | CHF 5–15 | Spread-based |
High-Risk Jurisdiction Surcharges Explained
Some banks quote additional onboarding or administration charges for complex cross-border relationships. There is no Swiss-wide annual surcharge schedule for nationality, political exposure or FATF jurisdiction. The fee table above is an editorial illustration, not a current price list: ask the chosen bank for a written schedule covering onboarding, account, custody, transfers, FX and investment services before committing funds.
Fee Negotiation Strategies That Work in 2026
- Deposit size leverage: clients depositing CHF 5M+ can often negotiate reduced maintenance fees and waived non-resident surcharges
- Service bundling: combining custody, investment management, and lending typically lowers aggregate fees versus individual service pricing
- Professional introductions: banks value referrals through established networks and frequently extend fee concessions to well-introduced clients
- Transparent risk profiling: comprehensive compliance documentation demonstrating a clean risk profile can minimise or eliminate high-risk surcharges
- Long-term commitment: expressing a multi-year relationship intention strengthens your negotiating position before account opening
7. Investment and Digital Banking Opportunities in 2026
Traditional Private Banking Investments
Swiss private banks provide access to the full investment spectrum. This includes Swiss government bonds and federal securities backed by AAA ratings (minimum CHF 10,000); diversified global equity and fixed income portfolios with professional management (CHF 100,000+ for retail clients, bespoke for family offices); private equity direct investments and fund participations (CHF 1M+ minimums); and hedge funds across long-short equity, global macro, and event-driven strategies.
Additionally, real asset exposure is available through precious metals custody, fine art financing, and structured product solutions. Swiss banks remain uniquely positioned to combine all these asset classes within a single, compliant relationship structure.
ESG and Sustainable Investing Leadership
Switzerland leads global ESG integration in banking. Lombard Odier pioneered carbon-neutral portfolios that embed climate considerations across all asset classes. Julius Baer, UBP, and Pictet integrate ESG screening criteria across traditional equity and fixed income holdings. Impact investment platforms now provide direct access to microfinance initiatives, renewable energy project finance, sustainable agriculture, and social impact bonds with measurable outcomes.
For clients who prioritise values-aligned investing, Switzerland offers an unmatched depth of institutional expertise. Furthermore, FINMA's 2026 green finance disclosure requirements are accelerating ESG integration across even smaller Swiss institutions.
Digital Banking, Robo-Advisory, and Crypto
Swissquote's robo-advisory platform manages portfolios at 0.95% per annum, with a CHF 10,000 minimum investment. AI-driven rebalancing, tax-optimised withdrawal strategies, and seamless integration with active trading accounts make it the leading digital solution for mass affluent non-residents. Dukascopy, IG Bank Switzerland, and Saxo Bank (Swiss) complement this offering with institutional-grade trading platforms.
For eligible cryptocurrency clients, Sygnum and Amina Bank offer regulated Swiss digital-asset services. Their products, custody terms and client criteria differ. Sygnum's CHF 50,000 figure is a starting deposit or trading-volume requirement for qualified private investors, not a universal crypto-portfolio minimum; it also lists a separate CHF 500,000 asset test for that client category. Confirm Amina's conditions and the transaction history each bank expects.
8. Real Client Cases — Anonymised
These three cases come from our client work. Client initials and institutions are withheld for confidentiality. Each outcome reflects one bank's assessment of one application; it is not an approval-rate claim or a promise of the same result.
Case 1: Mr. B — Central Asian Commodity Trader Resident in the UAE
Profile: Mr. B is a Central Asian commodity trader resident in the UAE. His business involves petroleum products and oil lubricants. He also had a former affiliation with local politics, which added questions to an already sensitive industry profile.
Challenge and approach: The application needed to explain the trading business, the origin of the assets to be banked, and the former political connection clearly enough for a Swiss bank's enhanced review. The point was to make those facts transparent rather than treat the political history or sector risk as a detail to omit.
Outcome: We helped Mr. B open a Swiss account with a reputable private-banking institution controlled by a cantonal bank. The bank's identity and account terms remain confidential.
Case 2: Mr. A — CIS Client with Crypto-Trading Wealth
Profile: Mr. A is from a CIS country and built his wealth through crypto trading. The origin and movement of digital assets made his case particularly challenging for conventional bank onboarding.
Challenge and approach: The key issue was presenting a coherent path from trading activity to the assets proposed for the account, including evidence a bank could assess under its own source-of-wealth and source-of-funds rules. A large portfolio alone would not answer those questions.
Outcome: We helped Mr. A open an account with a subsidiary of a long-established Swiss banking group with roughly 200 years of history. The institution and terms are withheld to protect client confidentiality.
Case 3: Mr. M — CIS Citizen Living in Cyprus, Online Gaming Wealth
Profile: Mr. M is a CIS citizen living in Cyprus whose wealth came from the online gaming industry. The sector, cross-border residence and wealth history made bank selection and documentation especially important.
Challenge and approach: The application had to give the bank a clear explanation of the business and how income from it became the assets to be transferred. Eligibility and evidence were assessed against the chosen bank's requirements.
Outcome: We helped Mr. M open an account at a private bank in Zurich. The client and bank remain anonymous.
9. Common Mistakes and Proven Success Strategies
Five Critical Mistakes That Cause Rejections of non-resident account applications
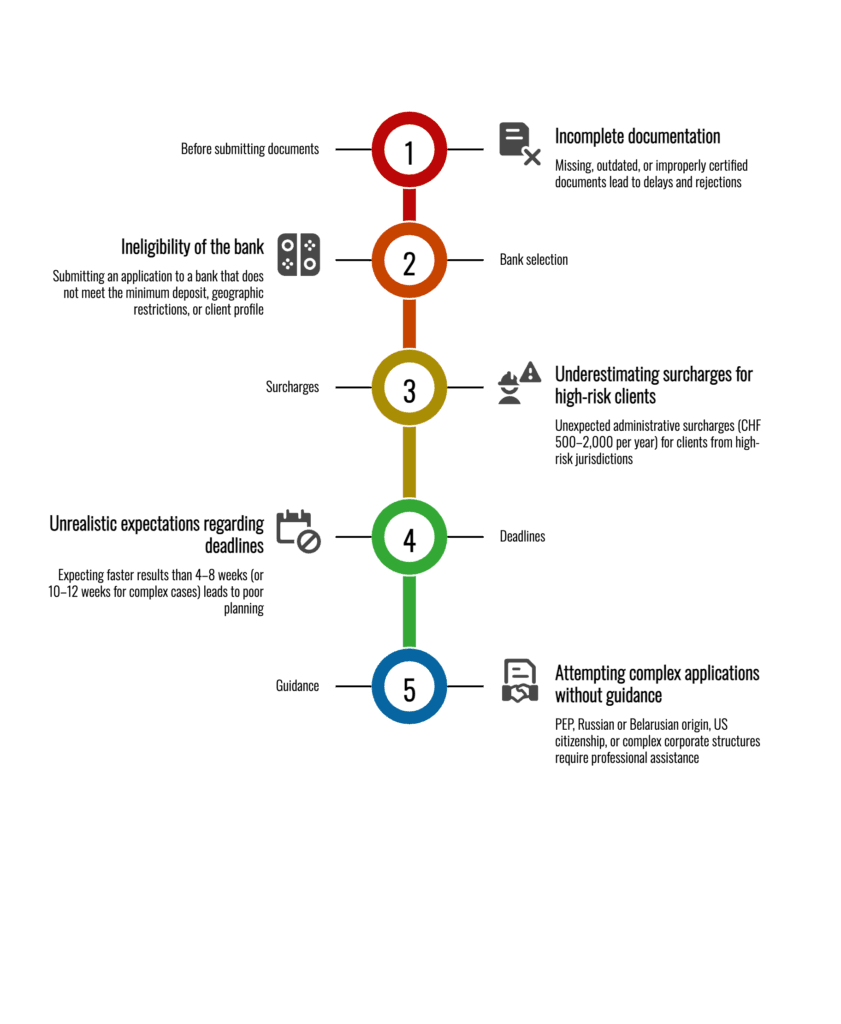
Mistake 1: Incomplete Documentation at Submission
This is the most common cause of delays and rejections. Missing, outdated, or improperly certified documents halt the process entirely. Furthermore, banks typically restart the compliance review clock when supplementary documents arrive weeks after initial submission. Fix: conduct a full documentation audit before submitting anything.
Mistake 2: Mismatched Bank Selection
Applying to a bank whose relationship size, geographic restrictions or client profile do not match yours can waste time. Fix: confirm eligibility and product fit before submitting documents. Target institutions genuinely suited to your situation.
Mistake 3: Underestimating High-Risk Surcharges
Clients from elevated-risk jurisdictions often apply without budgeting for CHF 500–2,000 in annual administrative fees. These are non-negotiable at many institutions. Fix: factor these surcharges into your long-term cost projections. Negotiate fee structures upfront where possible.
Mistake 4: Unrealistic Timeline Expectations
Swiss banks require 4–8 weeks minimum for proper compliance review. Expecting faster results leads to poor planning. Fix: apply well in advance of any funding deadline. Build buffer time for potential additional information requests. Complex cases routinely take 10–12 weeks.
Mistake 5: Attempting Complex Applications Without Guidance
Political exposure, sanctions-sensitive connections, US-person status and complex corporate structures can each require more careful bank matching and documentation. Fix: disclose the facts accurately, confirm the bank's policy and obtain specialist advice where your situation warrants it. Our Swiss bank account opening service explains the assistance we offer international clients.
Five Strategies That Maximise Approval Probability
- Conduct a mock compliance review before formal submission — identify red flags, documentation gaps, and narrative inconsistencies early
- Gain direct relationship manager introductions through professional networks — this bypasses cold-application screening layers entirely
- Communicate transparently about your compliance posture, fund sources, and business activities upfront — proactive disclosure builds trust
- Negotiate fee structures before signing — leverage deposit size, service bundling, and long-term commitment
- Maintain meticulous ongoing documentation — provide timely updates on material changes to preserve your banking relationship
10. Before You Apply: Five Checks That Save Time
1. Confirm the Bank Accepts Your Residence and Client Type
Start with the bank's eligibility rules for your residence, citizenship, tax status and intended account use. A bank may accept residents abroad but restrict the products it can offer them. Swissquote also specifies where the first transfer may originate; Sygnum says it does not onboard retail clients. Ask for the current criteria before collecting a full application pack.
2. Match the Product to Your Assets and Purpose
Separate an initial funding transfer from the assets a private bank expects in an ongoing relationship. A multi-currency payment account, trading account and discretionary wealth-management mandate are different products. Explain whether you need payments, custody, investing, lending or a relationship manager, then request a written indication of the relevant balance and fee schedule.
3. Reconcile Your Wealth Story with the First Transfer
Your source-of-wealth account should show how you built your assets over time. Your source-of-funds evidence should then follow the specific money or securities from their origin through any intermediate accounts to the account that will fund the Swiss bank. If you need a starting structure, use our source-of-wealth declaration template and adapt it to your records.
4. Agree the Identification Route Before Booking Travel
Ask whether your profile can be verified by video, whether originals or certified copies are required, and whether a relationship-manager meeting can be held remotely. An online application form does not guarantee that the whole process stays online; a bank can request an additional interview or in-person visit after its initial review. Our guide to opening a Swiss account remotely compares the video, online and postal routes and what each one needs from you.
5. Check the Full Cost and the Decision Maker
Compare account and custody fees, foreign-exchange spreads, investment charges and any surcharge for residence abroad. For example, PostFinance lists a CHF 25 monthly charge per payment account for clients domiciled abroad, regardless of assets. Ask which bank team approves your client category and what additional evidence could delay the decision. If a private-banking introduction would help, our application service explains its scope separately from this guide.
11. The Future of Cross-Border Swiss Banking for Non-Residents
Rules for serving a client across a border are changing, but the practical question remains the same: which Swiss entity can offer your account and services where you actually live? These five developments matter as of September 2026.
EU clients: CRD VI changes active banking from January 2027
From 11 January 2027, Article 21c of the EU's CRD VI generally requires a non-EU bank actively providing core banking services, including standalone deposit-taking and lending, into an EU member state to use an authorised local branch or EU subsidiary, unless an exception applies. It does not ban an EU resident from holding or applying for a Swiss bank or custody account, as the Swiss Bankers Association explains.
A genuine request made entirely on the client's own initiative can fall under reverse solicitation; a bank or introducer cannot manufacture that initiative through targeted promotion. CRD VI also carves out MiFID investment services and genuinely related ancillary deposits or credit. That makes wealth management and investment mandates different from marketing a standalone savings account or loan into the EU, but it is not a blanket exemption for every private-banking product. The bank must check the service, client category and member-state rules before approaching an EU resident. See the European Banking Authority's Article 21c analysis.
Gulf clients: more interest, closer checks on real residence
Following the Middle East conflict, Reuters reported in March 2026 that Gulf-based clients were exploring Swiss bookings and bankers expected more inflows. That reporting describes inquiries and expectations, not a measured wave of completed transfers from the UAE. A client presenting UAE residence should be ready to reconcile their actual home, tax residence, business ties and origin of assets. A residence card alone may not resolve a file if the wider evidence points elsewhere: Swiss AEOI rules require banks to establish the client's tax residence, while FINMA expects detailed checks for higher-risk wealth and jurisdictions.
Some banks may narrow their accepted residence and citizenship combinations or favour markets they know well, including Switzerland, the EU, the UK or their own home market. That is a bank-specific risk decision, not a Swiss-wide rule excluding UAE residents or other nationalities. Ask the proposed bank which legal entity would serve you and what evidence it requires for your real residence and funding route.
Israeli clients: specific permissions for cross-border investment activity
Israel shows how a defined cross-border route can work without granting every Swiss bank unrestricted access. Deutsche Bank (Switzerland) says the Israel Securities Authority confirmed it may approach eligible Israeli investors, subject to disclosures. Dreyfus Banquiers discloses an ISA Section 49A permit for brokerage services to clients domiciled in Israel. UBS describes a separate foreign-dealer registration for investment marketing through its Israeli entity. These are different permissions, not a blanket approval for deposits, lending, advice or every Israeli client. Ask which bank entity, service and client category a particular authorisation covers.
UK clients: the Berne agreement opens a defined investment route
The Berne Financial Services Agreement took effect on 1 January 2026. Eligible Swiss firms that complete the notification and registration process can provide certain cross-border investment and ancillary services to UK high-net-worth clients, professional clients and eligible counterparties without separate UK authorisation for those covered activities. It does not open every retail banking, deposit or lending service to every UK resident. For a prospective client, the useful question is whether the Swiss firm is on the relevant register and whether the proposed service and client classification fall within its scope.
Digital competition: watch Revolut's Swiss licence application
Revolut announced on 16 September 2026 that it had applied for a Swiss banking licence; FINMA's decision is still pending. If approved, it plans Swiss IBANs and local payment products. This could increase pressure on everyday banking fees and digital service, but Revolut has not announced a Swiss non-resident eligibility policy or a low minimum deposit for a future Swiss bank. Bespoke wealth management involves different services and compliance work; a digital challenger may influence client expectations without replacing those relationships.
What to do now: Define whether you need payments, deposits, credit, custody or investment advice; identify your genuine residence and tax residence; then ask the bank which entity can lawfully provide each service to your profile. A cross-border permission is not the same as account-opening approval.
12. Frequently Asked Questions — Open a Swiss Bank Account (2026)
For U.S. citizens and clients living in the USA, read our September 2026 audit of Swiss bank accounts for U.S. clients. It separates FATCA reporting, Swiss custody, U.S. securities-advice rules and each bank’s decision to accept a client. This guide does not establish that any named bank is available to a particular U.S. person.
Official checks: Review SECO sanctions, Swiss AEOI/CRS guidance, crypto-asset reporting status, and esisuisse deposit protection before acting on the FAQ. Bank terms should be confirmed with the institution.
Conclusion: Your Roadmap to Open a Swiss Bank Account in 2026
Switzerland remains a major centre for cross-border wealth management. To open a Swiss bank account as a non-resident in 2026, you need three things above all others: a documented source of wealth and funds, the right bank for your profile, and realistic expectations about eligibility, costs and timing. If a previous application was declined, our separate guide to Swiss account rejections explains how to review the cause before applying again.
The regulatory complexity that deters unprepared applicants creates a structural advantage for those who approach the process correctly. FINMA-backed institutional resilience, CHF 100,000 deposit protection, access to global investment markets, and 25% of all global cross-border assets under management make Swiss banking worth pursuing — when pursued strategically.
Before you apply, take two important steps. First, use our free AML Risk Score Calculator to identify any compliance risk factors in your profile. Second, review our Swiss bank account opening service to understand how we support non-residents through every stage — from bank selection and documentation preparation to relationship manager introductions and ongoing compliance support.
The keys to success are consistent across all client profiles: prove the legal origin of your funds, submit complete documentation on the first attempt, target institutions genuinely suited to your situation, and engage expert guidance whenever complexity arises.
Swiss private banking application
Ready to see which Swiss banking route fits your profile?
If you are a non-resident with CHF 500,000 or more in investable assets, start with a free eligibility review. We assess your residence, source of wealth, account purpose and documentation before discussing a suitable application route.
Start your Swiss bank applicationThe bank decides whether to accept an account or financing request. An eligibility review is not an approval guarantee.
Disclaimer: Bank-specific examples and cited conditions were reviewed on 23 September 2026; other figures in this guide are indicative. Swiss business account requirements evolve rapidly. All information should be verified directly with the relevant institution or a qualified Swiss banking advisor before taking action. This document does not constitute financial, legal, or tax advice.